Insurance Claims
How to file a roof insurance claim.
Filing a roof claim in Texas is more straightforward than most homeowners expect — especially with a roofer who does it every week. Here’s the process, step by step, and exactly where we step in.
- GAF Certified · Factory-certified installer
- 10-Year · Workmanship warranty
- Family-Owned · Houston since 2023
The process
Step by step — and where we step in
- 01
The inspection & the honest recommendation
We assess the roof, identify legitimate storm damage, and tell you whether filing a claim makes sense. No pressure either way.
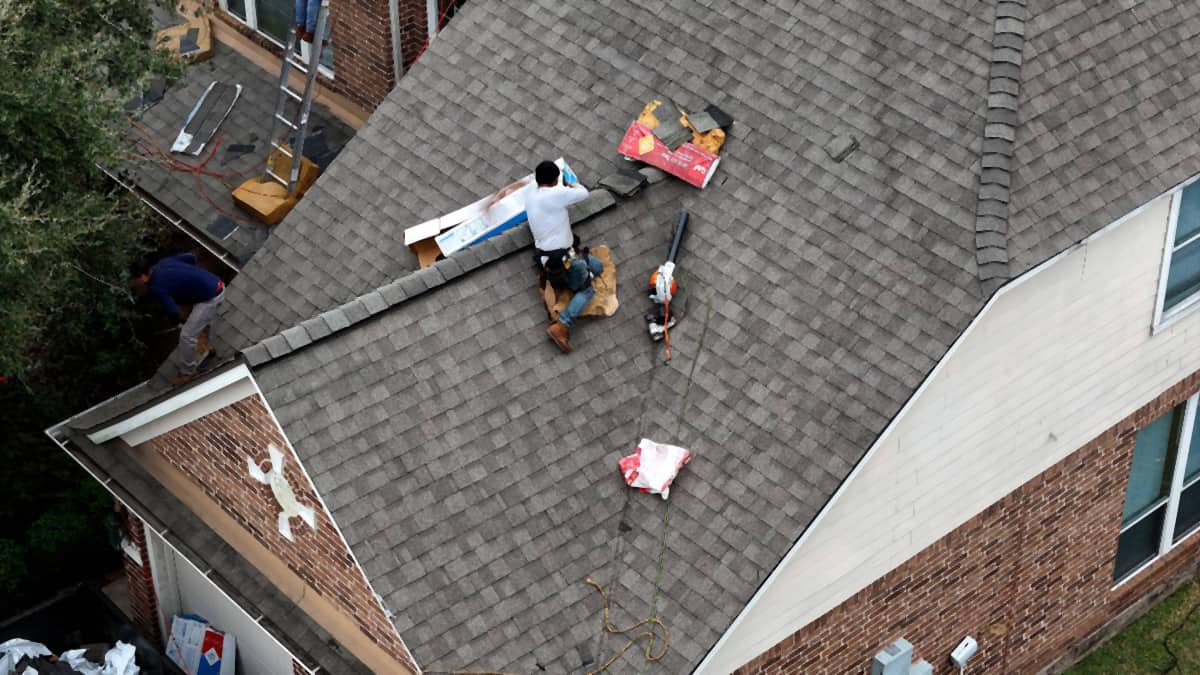
One crew member, one section at a time. This is what most of a roof day actually looks like — slow, close-in work on a single plane. - 02
Filing the claim — together, in person
When it makes sense to file, we recommend filing with our guidance — and it's our standard to be there with you when you do. Why in person? Because we want to make sure your claim gets a real, in-person adjuster inspection — someone who actually gets up on the roof. A drone flyover alone isn't enough to make a fair coverage decision, and we push for a proper look.
- 03
The adjuster meeting — we don't leave you (or the adjuster) alone up there
When the insurance adjuster comes out, we meet them on the roof and walk them through our findings. We don't leave the adjuster up there to evaluate it alone. We're there to make sure the damage is seen, documented, and fairly evaluated — so nothing legitimate gets missed or waved off.
- 04
The first letter — where the process really begins
This is the step that trips up almost everyone. The first letter from the insurance company often looks like a denial, or comes back "under your deductible." Most homeowners read that and quit — and that’s the mistake. But if the insurer has acknowledged storm damage at all, that’s our green light — because now it’s about documenting the legitimate storm damage that’s there, so the full, fair scope of repair or replacement is on the record. Insurance is naturally conservative; the first number is rarely the real number.
- 05
Approval — still not the finish line
Even after approval, insurers tend to underpay. They'll leave line items out of the estimate — things genuinely required to do the job right. That's not your problem to catch. It's ours.
- 06
Supplementing what’s owed
After the work is done, we document and submit a supplement for the legitimate items the initial estimate left out — things like starter strip, valley metal, non-nailable decking, and painting of rooftop accessories. These are standard parts of a real roof replacement that insurers routinely omit, and we go back and claim them properly.
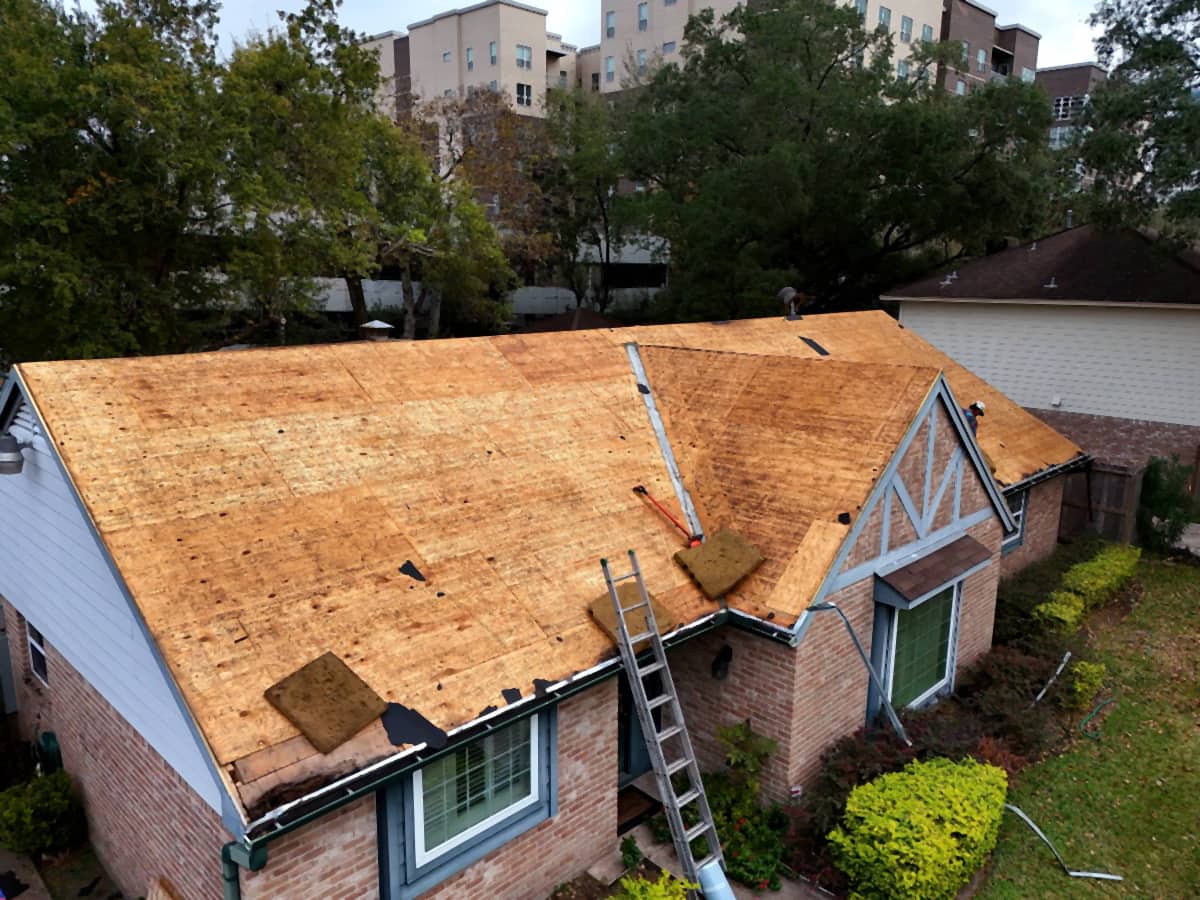
A Spring Branch roof down to bare plywood. Every sheet gets walked and checked at this stage — soft decking gets replaced before anything goes over it. - 07
The net claim, the deductible & recoverable depreciation
Once approved, the insurer issues the net claim — the total replacement cost minus depreciation minus your deductible. When materials are delivered, we collect the deductible from you. On completion, we submit our certificate of completion and final supplemented estimate along with the deductible payment — and that’s what triggers the insurer to release the recoverable depreciation (the rest of what’s owed).
We can't promise an outcome — coverage decisions are the insurer's. What we promise is the work: a thorough inspection, complete documentation, our presence at the adjuster meeting, and a proper supplement for what's owed.
Free · instant · no phone number needed
Find the storm date for your address
Enter your address and we'll show you every hail and damaging-wind report NOAA recorded near it since 2019. Knowing the date a storm hit your roof is the single most useful fact in an insurance claim — and this costs you nothing.
Source: NOAA / NCEI Storm Events Database — reports filed by trained spotters, officials and the public. These are reports, not radar coverage: if nothing shows up near you it means nobody filed a report there, not that no hail fell. The only way to know what your roof actually took is to look at it.
Free, no-pressure
Get your damage documented — free
Before you file, after a denial, or mid-claim — we document the damage properly and stand with you through it. You get photos of every problem area, written findings in plain English, and a repair estimate if a repair is the honest answer. Emailed to you and left with you in print — yours to keep, whether you hire us or not.
- Photos of every problem area on your roof
- Written findings, in plain English
- A repair estimate, if a repair is the honest answer
If it's storm damage, we handle the insurance claim with you. Financing available.
Roof leaking? We answer 24/7 — call any hour. Or email Aldo@handyhandsroofing.com
Get your free roof report
Name and phone is all we need — we'll call you back. No obligation.
Got it — we have your details
Thanks — we’ll contact you about your request. Prefer to talk now? Call (346) 276-6492.
GAF Certified · 10-Year Workmanship Warranty · Insurance restoration specialists